Owning the building your restaurant operates in is one of the best moves a restaurateur can make. You control your space, you are not at the mercy of a landlord, and every payment builds equity. But many South Bay restaurant owners who bought with an SBA 504 loan around 2016–2017 are about to hit a date they may not have marked on the calendar.
Get a free loan due-date and building value review →
Why 2026–2027 matters
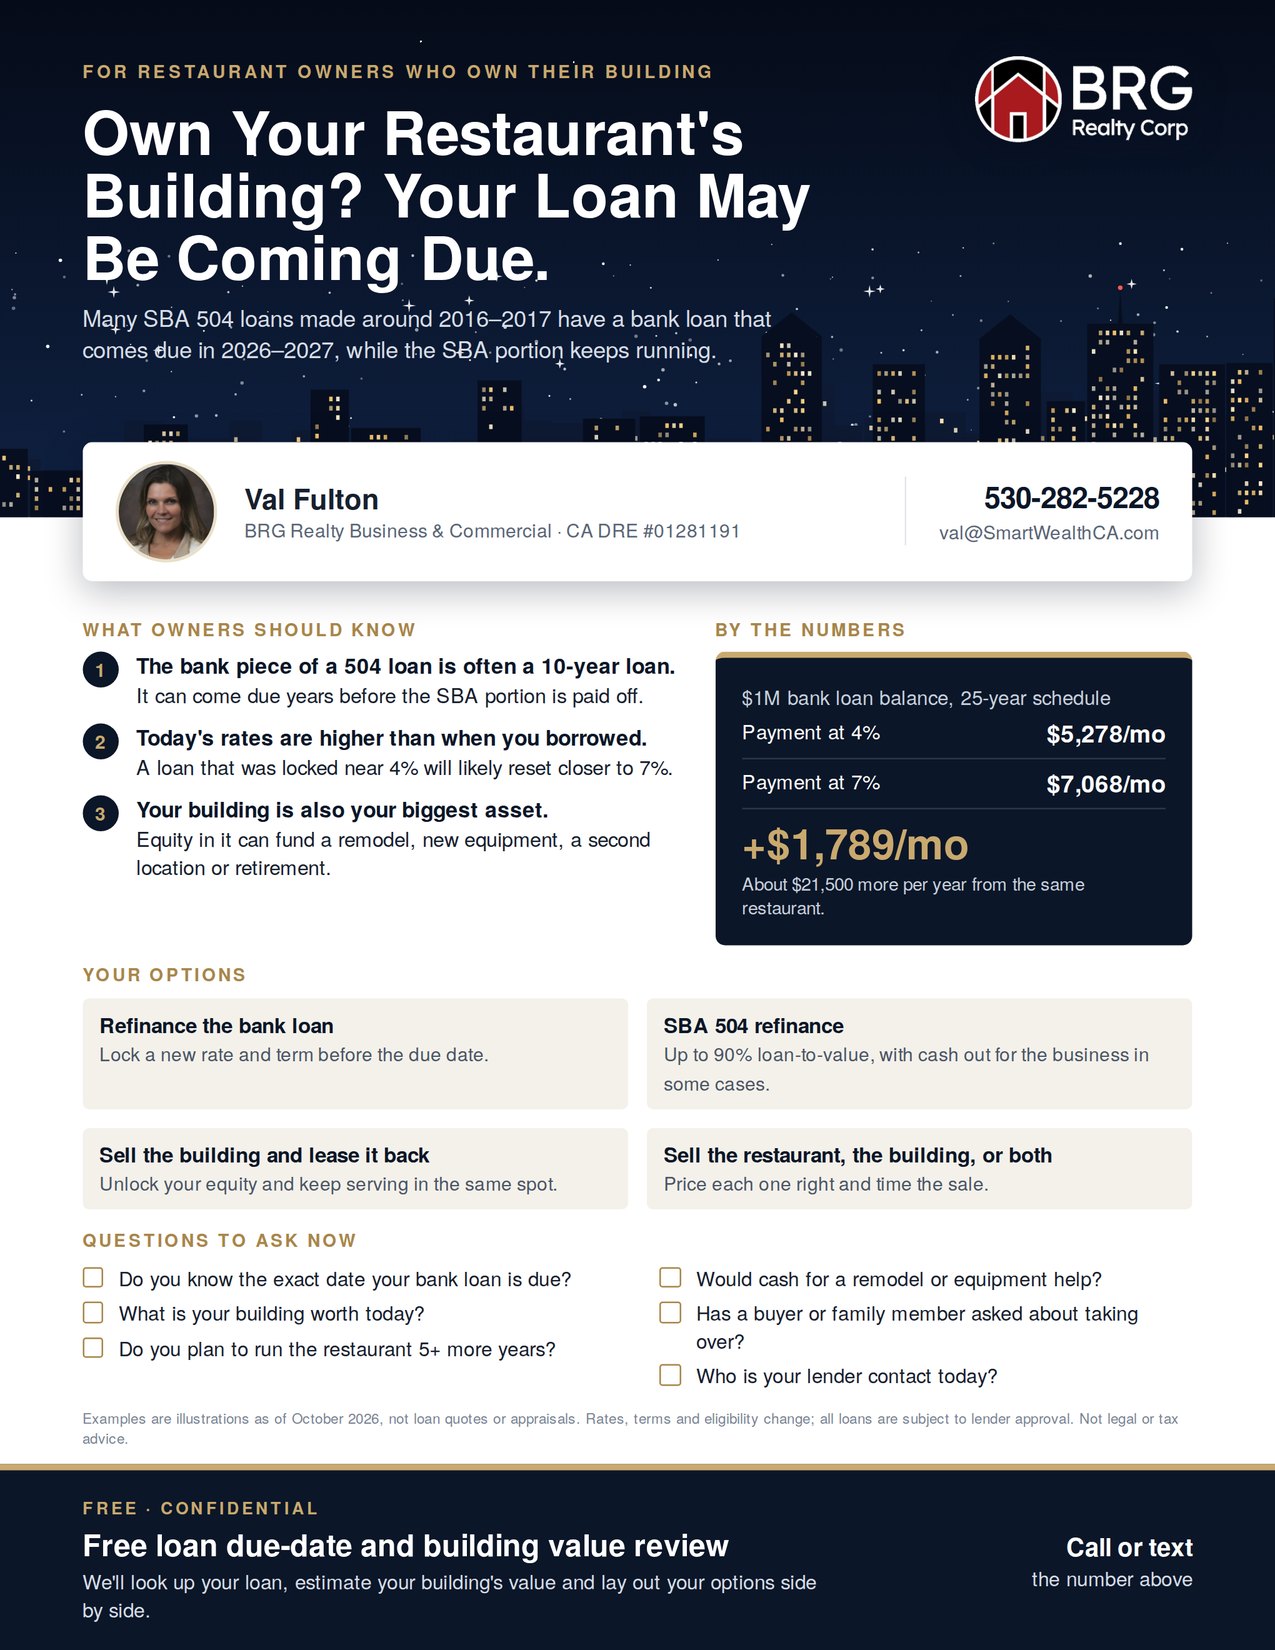
An SBA 504 loan is really two loans. A bank makes a first loan (usually about half the project) and a Certified Development Company makes the SBA-backed second loan (about 40%). The SBA portion often runs 20 or 25 years at a fixed rate. The bank portion, though, frequently has a 10-year term on a longer payment schedule. That means a large balance can come due ten years after you closed, even though the SBA piece keeps running.
What a reset can cost
On a $1 million bank loan balance on a 25-year schedule, the payment at 4% is about $5,278 a month. At 7% it is about $7,068, roughly $21,500 more a year from the same dining room. For a business that runs on thin margins, that is worth planning for.
Your options
- Refinance the bank loan before it comes due, with your current lender or a new one.
- Use an SBA 504 refinance. Businesses operating at least two years can refinance up to 90% of the property value, and in some cases take cash out for business expenses like a remodel or new equipment.
- Sell the building and lease it back. Unlock your equity and keep serving customers in the same location.
- Sell the restaurant, the building, or both. Many owners sell the business and keep the real estate as long-term rental income.
Questions to ask now
Do you know the exact date your bank loan is due? What is the building worth today? Do you plan to run the restaurant for at least five more years? Has a family member, manager or buyer asked about taking over? Your answers point to the right option, and starting 6–12 months before the due date keeps all of them open.
Download the one-page guide
Download the restaurant owner guide (PDF)
Examples are illustrations as of October 2026, not loan quotes or appraisals. Rates, terms and eligibility change, and all loans are subject to lender approval. This is general information, not legal or tax advice.