Owner-occupied industrial and flex buildings in Campbell, San Jose and Los Gatos are hard to replace. If your contracting, trade or auto business owns its shop, yard or warehouse, that property is probably one of your biggest assets, and it deserves a plan.
Get a free building value and loan review →
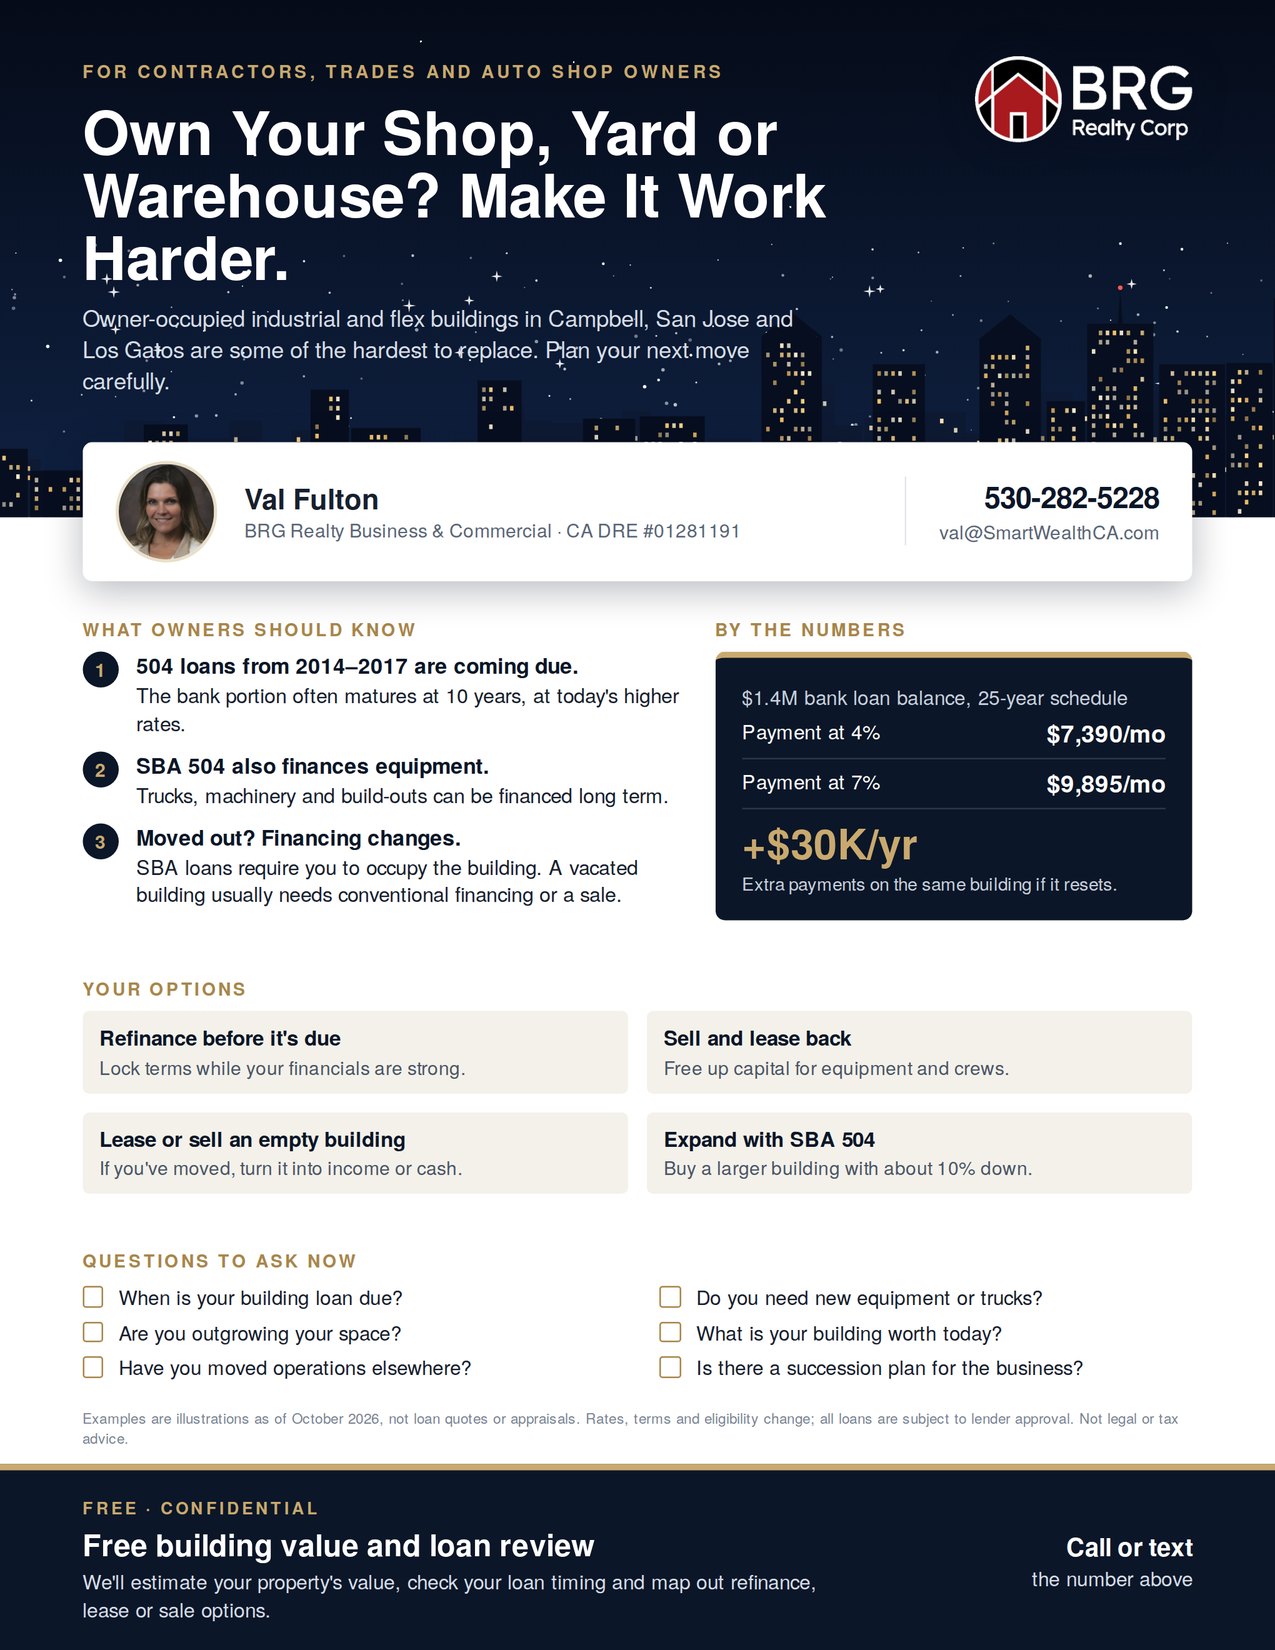
Loans from 2014–2017 are coming due
Many trade businesses bought their buildings with SBA 504 loans. The bank portion of those loans often has a 10-year term, so loans from 2014 to 2017 are maturing now. On a $1.4 million balance on a 25-year schedule, the payment at 4% is about $7,390 a month. At 7% it is about $9,895, roughly $30,000 more a year.
SBA 504 is not just for buildings
The same program can finance long-life equipment, machinery and build-outs on long, fixed-rate terms. If you are planning a refinance, it may make sense to roll in an equipment purchase at the same time.
Moved out of your building?
SBA loans require the business to occupy the property. If you have moved operations to a new location, the old building usually needs conventional financing, a lease to a tenant or a sale. An empty building is costing you money; leased or sold, it can fund the next stage of your business.
Your options
- Refinance before the loan is due, while your financials are strong.
- Sell and lease back to free up capital for equipment and crews.
- Lease or sell a building you have moved out of.
- Expand with SBA 504 into a larger building with about 10% down.
Questions to ask now
When is your building loan due? Are you outgrowing your space? Do you need new trucks or equipment? What is the building worth today? Is there a succession plan for the business?
Download the one-page guide
Download the contractor and trades guide (PDF)
Examples are illustrations as of October 2026, not loan quotes or appraisals. Rates, terms and eligibility change, and all loans are subject to lender approval. This is general information, not legal or tax advice.