Many dentists, physicians and specialists in San Jose and the surrounding area own the building their practice operates in, often bought with an SBA 504 loan. That gives you two valuable assets: the practice and the real estate. Planning them together usually produces a better result than dealing with each one when the time comes.
Get a free practice and property options review →
The practice and the building can go separate ways
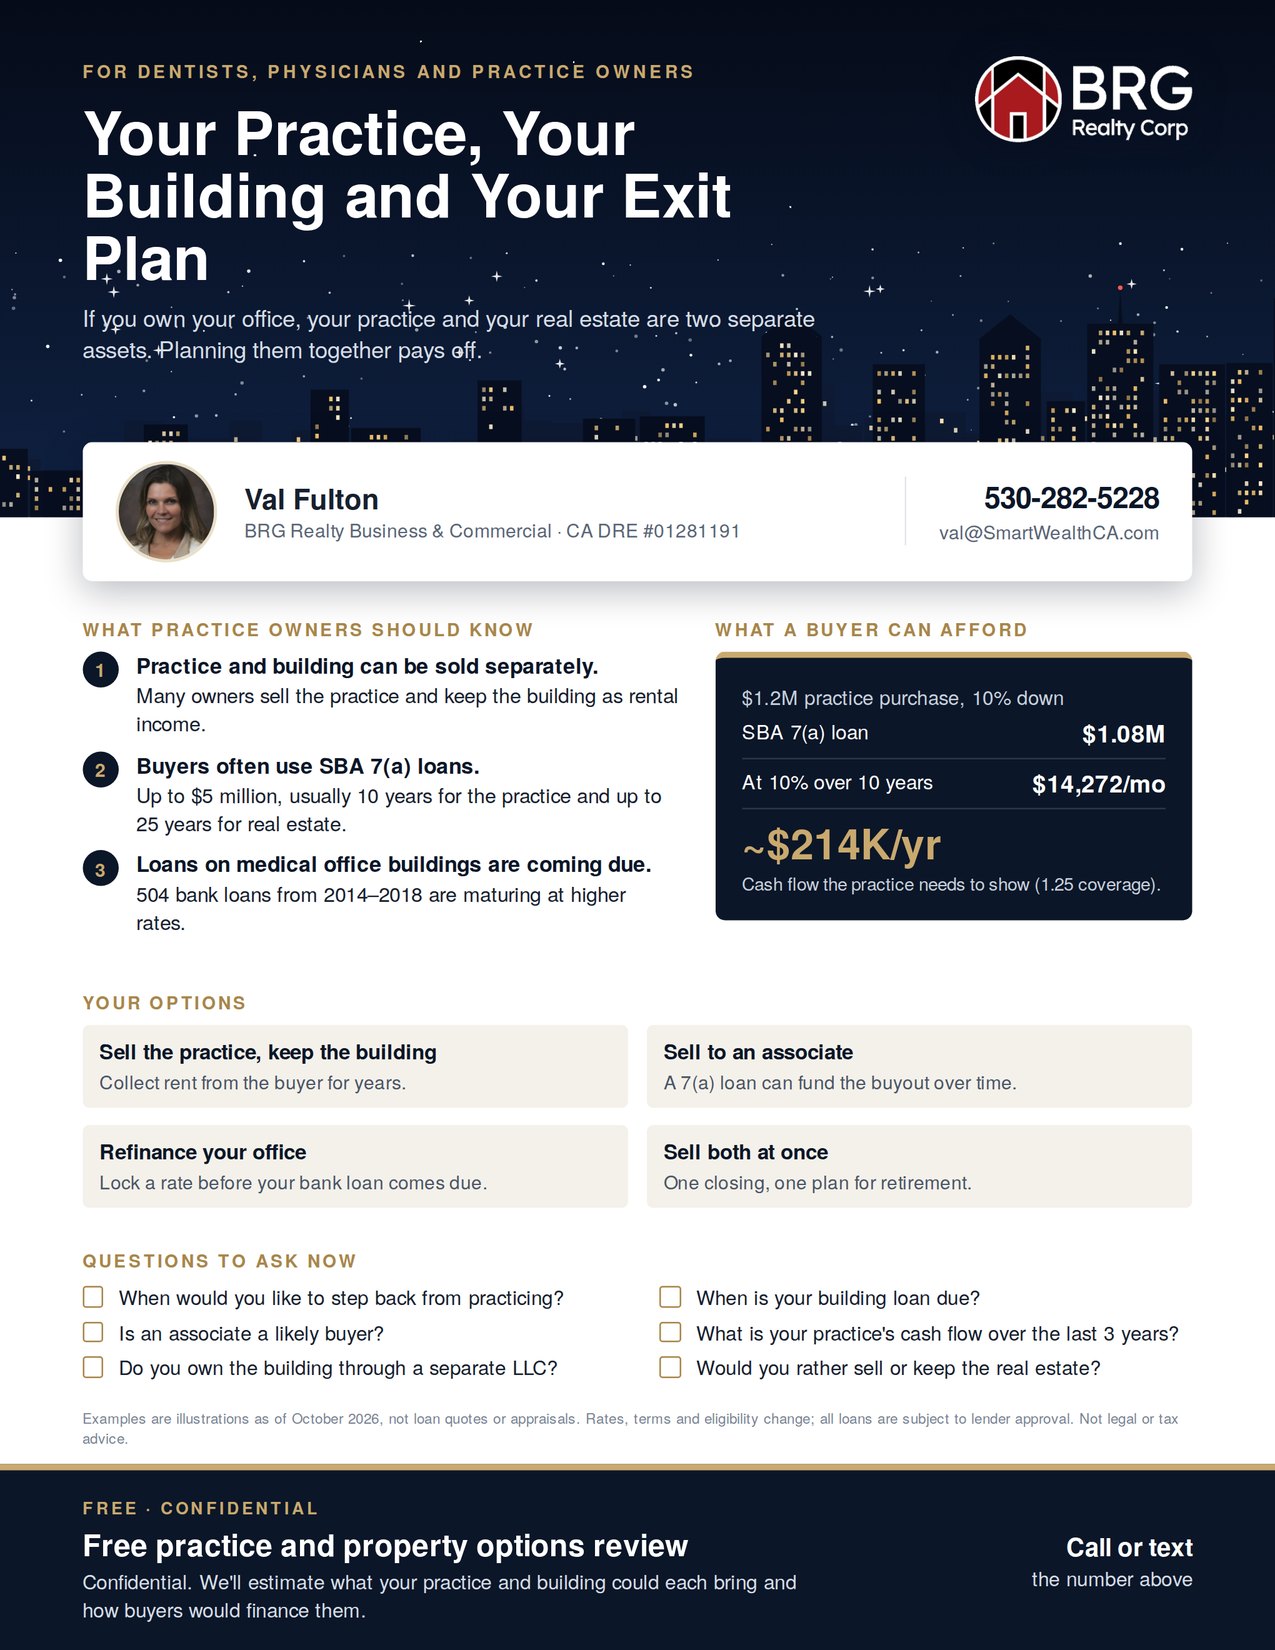
A common plan is to sell the practice to a buyer and keep the building, leasing it to the new owner. You receive the sale proceeds for the practice and keep collecting rent for years. Another is to sell both in a single transaction. Which one is better depends on your retirement plans, taxes and how much you want to stay involved.
How buyers pay for practices
Most practice buyers use an SBA 7(a) loan, up to $5 million, typically with a 10-year term for the practice and up to 25 years for real estate. On a $1.2 million practice purchase with 10% down, the loan is $1.08 million. At 10% over 10 years, the payment is about $14,272 a month. Lenders usually want to see about 1.25 times that in cash flow, around $214,000 a year, so clean books and three years of tax returns are essential.
Associate buyouts
If you have an associate who could take over, an SBA 7(a) loan can finance the buyout over time. Under current SBA rules, if you keep any ownership after a partial sale, you will need to personally guarantee the loan for two years, so plan the timing of a full exit carefully.
Don't forget the building loan
504 bank loans made between 2014 and 2018 are now maturing at higher rates. Refinancing before you sell, or lining up a sale that pays off the loan, avoids a surprise in the middle of a transition.
Questions to ask now
When would you like to step back from practicing? Is an associate a likely buyer? Is the building in a separate LLC? When is your building loan due? Would you rather sell the real estate or keep it as income?
Download the one-page guide
Download the practice owner guide (PDF)
Examples are illustrations as of October 2026, not loan quotes or appraisals. Rates, terms and eligibility change, and all loans are subject to lender approval. This is general information, not legal or tax advice.