SBA loans are still one of the best ways for a small business to buy a building, buy another business or refinance debt, but the rules changed in 2025 and 2026. Here are the current numbers and four examples that show how the math works.
Get a free SBA loan options review →
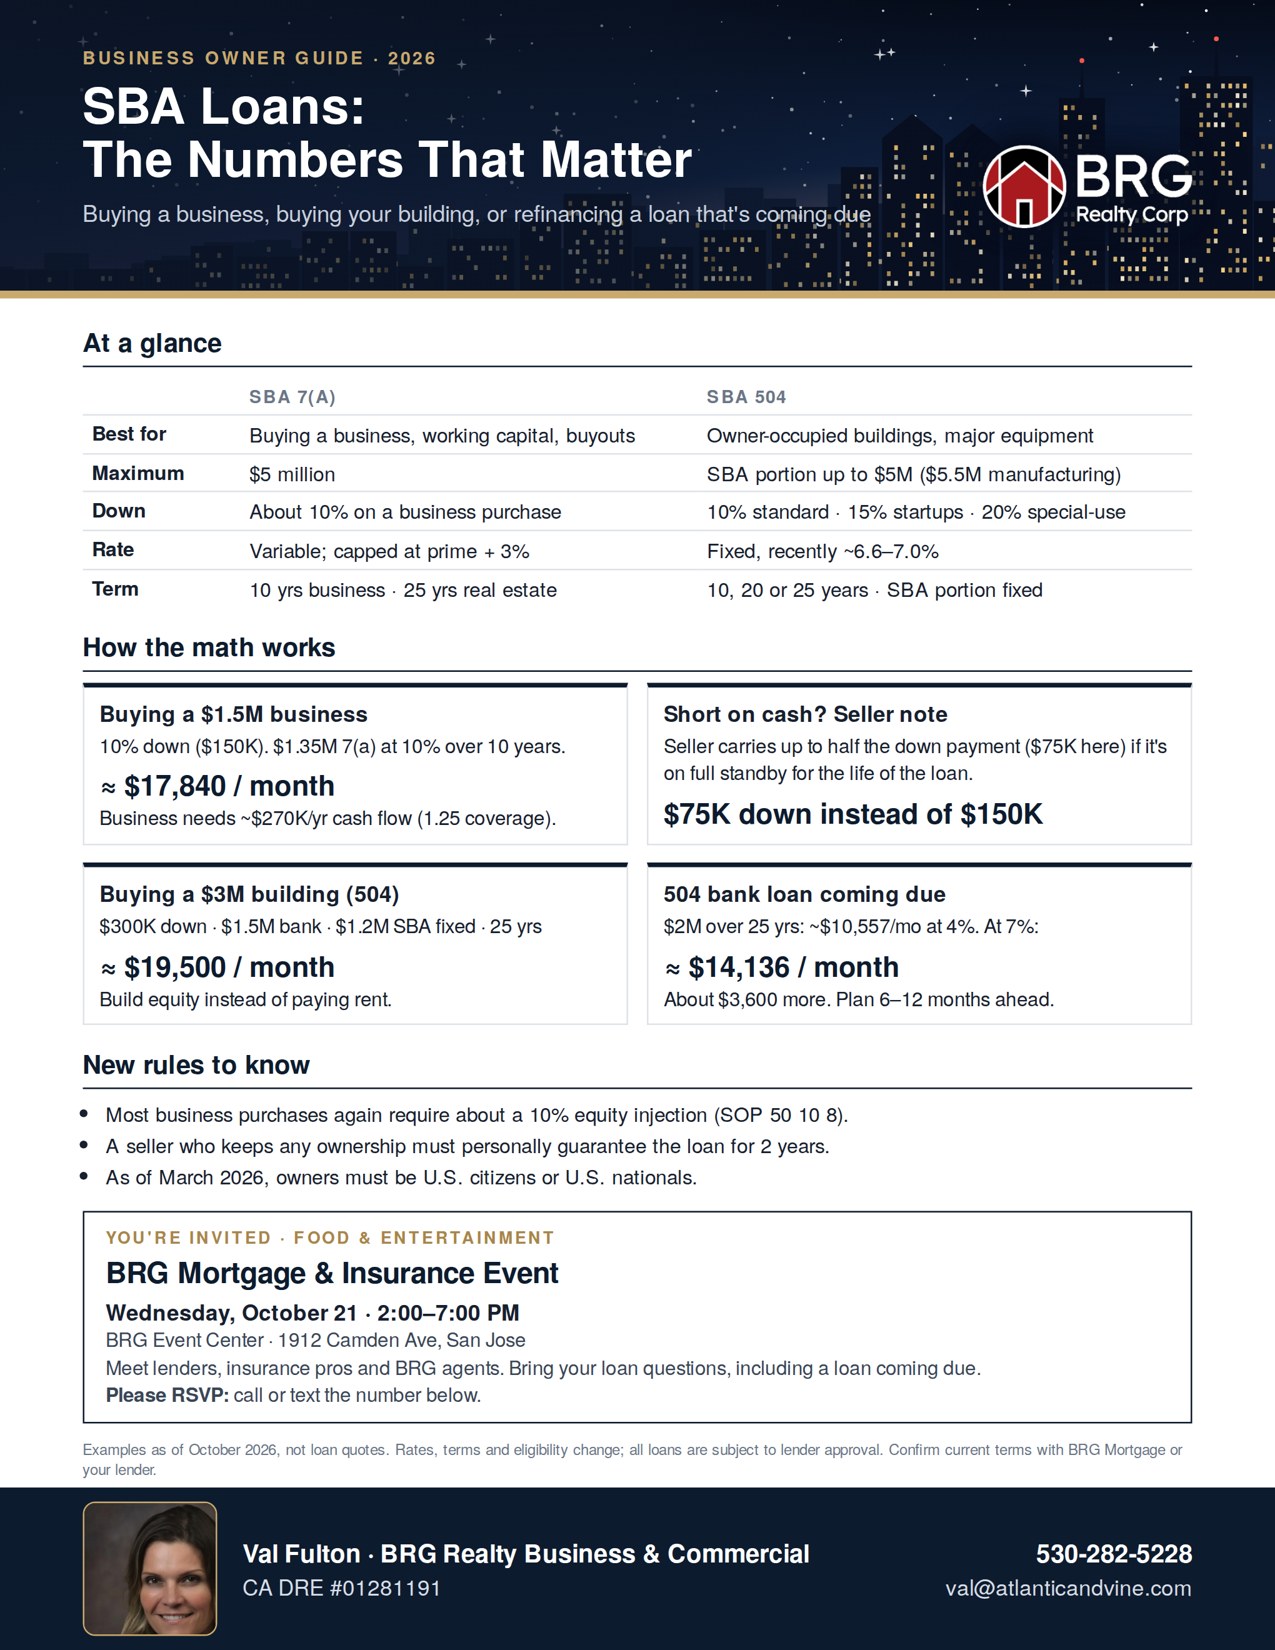
The 2026 numbers at a glance
| SBA 7(a) | SBA 504 | |
|---|---|---|
| Best for | Buying a business, working capital, partner buyouts, mixed-use deals | Buying or building owner-occupied commercial property and major equipment |
| Maximum | $5 million | SBA portion up to $5 million ($5.5M for manufacturing/energy); total project can be much larger |
| Down payment | Typically 10% equity injection on a business purchase | 10% standard; 15% for startups; 20% for special-use buildings |
| Rate | Usually variable, tied to prime (cap of prime + 3% on loans over $350K) | SBA portion fixed, recently around 6.6–7.0% |
| Term | Up to 10 years (business), 25 years (real estate) | 10, 20 or 25 years |
| Occupancy | 51% owner-occupied for real estate | 51% existing buildings, 60% new construction |
What changed
- Equity injection is back. Under the current SBA rules (SOP 50 10 8), most business purchases need about 10% down.
- Seller notes have limits. A seller note can cover up to half of the down payment only if it is on full standby (no payments) for the life of the SBA loan.
- Partial sales need a guarantee. If the seller keeps any ownership, they must personally guarantee the loan for two years.
- Ownership eligibility tightened. As of March 2026, owners must be U.S. citizens or U.S. nationals.
Scenario 1: Buying an established business
A buyer purchases a business for $1.5 million. With 10% down ($150,000), the SBA 7(a) loan is $1.35 million. At 10% over 10 years, the payment is about $17,840 a month, or $214,000 a year.
Lenders typically want a debt service coverage ratio of at least 1.25, so the business needs roughly $270,000 a year in cash flow available for debt payments. Clean books and three years of tax returns make or break this approval.
Scenario 2: Using a seller note
Same $1.5 million business, but the buyer has only $75,000 in cash. The seller carries a $75,000 note for the other half of the down payment, on full standby for the life of the loan. The seller gets paid later, the buyer gets in sooner, and the deal can still qualify.
Scenario 3: Buying your own building with an SBA 504
A business owner buys a $3 million building. The 504 structure splits the deal 50/40/10:
- Owner down payment (10%): $300,000
- Bank first loan (50%): $1.5 million at about 7.5% over 25 years ≈ $11,085/month
- SBA/CDC second loan (40%): $1.2 million at about 7% fixed over 25 years ≈ $8,481/month
Total: about $19,500 a month, and the owner is building equity instead of paying rent, with a long-term fixed rate on 40% of the project.
Scenario 4: A 504 bank loan coming due
Many 504 loans made around 2016 have a bank first loan with a 10-year term that comes due in 2026–2027, while the SBA portion keeps running. An owner with a $2 million balance who locked in at 4% has been paying about $10,557 a month. At 7%, the same balance costs about $14,136 a month, roughly $3,600 more.
Options include refinancing with the current bank, shopping other lenders, a 504 refinance (up to 90% loan-to-value, or 85% with cash out, for businesses operating at least two years), or selling or leasing back the property. Starting 6–12 months before the due date leaves the most room.
Quick answers
Can I use SBA to buy an investment property? No. SBA real estate loans require the business to occupy most of the building.
Can I combine buying a business and its building? Yes. A 7(a) loan can cover both, with the real estate portion on a longer term.
How long does approval take? Often 45–90 days, depending on how prepared the file is.
Download the one-page SBA guide
Figures are examples as of October 2026, not quotes. Rates, terms and eligibility change and every loan is subject to lender approval. Please confirm current terms with BRG Mortgage or your lender.